Stock Story: Crown Castle
Rates are up, infrastructure and bonds are down. Which is a better bet from here?
Higher yields have increased the prospective returns for bonds and infrastructure equities. We prefer the real growth that listed infrastructure has to offer. Crown Castle (CCI) is a highly predictable free cash-flow-generating business offering a compelling 6.2% yield combined with underlying structural growth.
Crown Castle is a US listed Tower REIT with an irreplaceable set of infrastructure assets
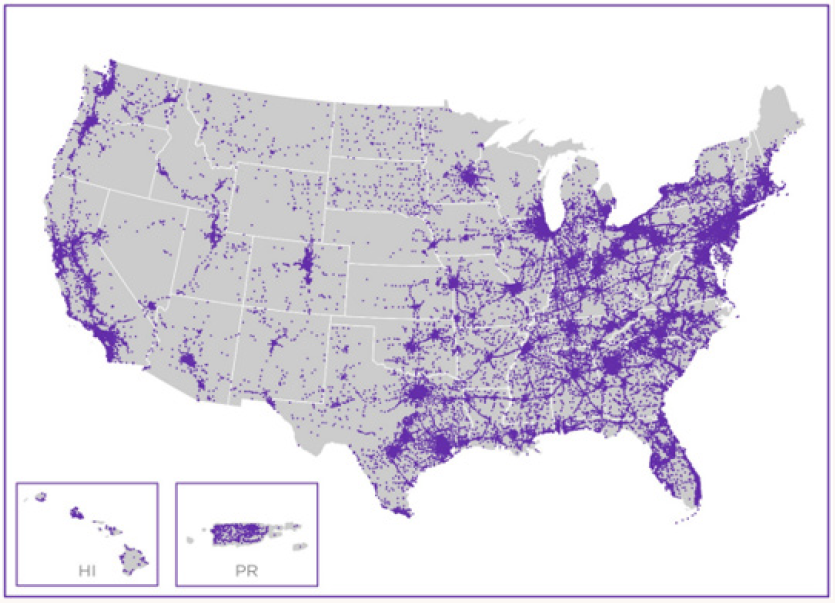
Crown Castle is one of the largest operators of telecommunications infrastructure in the US, where it provides the locations for telecommunication companies to site their active equipment such as antennas. Built or acquired between 1995 and 2013, many of these cell sites a tower or change the location of a tower due to network engineering challenges, permitting and NIMBY-ism. Figure 1 shows CCI’s existing tower footprint across metro areas and busy transport links.
Figure 1: Crown Castle tower asset portfolio overview
Crown Castle operates ~39,700 tower & rooftop sites across the US. The portfolio skews to metro areas compared to peers. Approximately 71% of their towers are located in the top 100 trading areas in the US.
Source: CCI Company Documents
How CCI makes money: A beautifully simple business model
Predictable cash flow streams, high margins and strong operating leverage: towers are the infrastructure sector’s version of the SAAS business model without the potential of disruption from AI.
To keep up with the surge in data use, telcos (tower customers) had no choice but to keep investing in their networks. This pressure began with the launch of the iPhone in 2007, intensified when 4G technology arrived in 2009, and grew again in the mid-2010s as social media apps drove a boom in video streaming. Between 2015 and 2025, mobile data traffic in North America grew by an average of 25% per year, according to Ericsson.
Over time, CCI’s rental income has expanded as they lease out more space on each tower to additional telecom tenants as well as larger, heavier antennas and radio equipment to existing customers to add more capacity in that local area. Additional revenue comes with high incremental margins as the cost to maintain a tower does not increase materially with more customers or equipment. Most costs are highly visible and fixed and include land lease costs, real estate taxes, insurance and site maintenance. Therefore, a high proportion of the extra revenue drops to the bottom line.
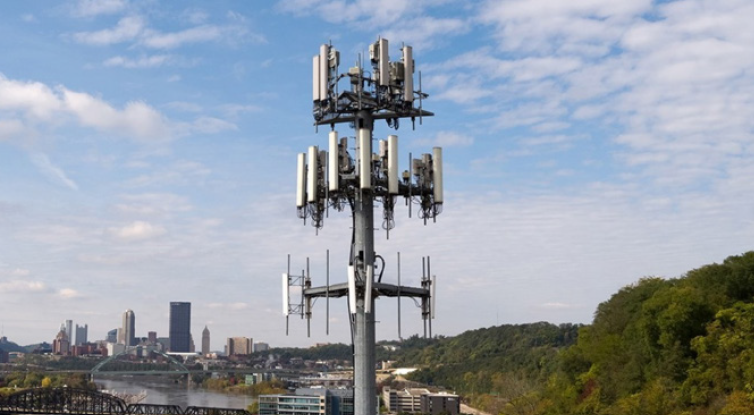
Each tower (see Figure 2) generates on average ~US$95k per year, rents escalate at ~3% under long-term contracts, and costs remain predictable. This is a simple, forecastable business model that compounds over time, underpinned by irreplaceable infrastructure that keeps the world connected.
The market has punished towers over the past 5 years but we see a turning point in the narrative
Calling the bottom for towers over the past 5 years has been a lot like catching a falling knife. While interest rates are the key contributor (to be discussed later), we’d also point to 3 additional reasons for their poor performance and why we see a turn in the narrative on each point.
1. Poor capital allocation: Crown spent much of the last decade piling capex into the untested and unprofitable fibre and small cell business. In 2025 CCI announced the sale of this business line and the replacement of management, returning the business to a higher-quality, free cash-flow-generating pure-play US TowerCo.
2. Customer consolidation and bankruptcy after a period of strong mid-single-digit growth through to 2024: CCI suffered two material churn events due to the merger of T-Mobile and Sprint, followed by the default of a new market entrant, DISH. These churn events were one-off in nature and not representative of a business model in decline. 2026 marks the completion of the bulk of these two revenue loss events. The prospects for growth in 2027 have improved materially.
3. Investor fear of satellites and the Elon Musk effect: The incredible success of the Starlink business and IPO of SpaceX has called into question the longevity of these tower assets by investors who do not specialise in infrastructure. We believe there are limitations in physics (something AI and lower launch costs cannot change) that prevents towers – even in many rural areas – from being disrupted by direct-to-device satellite communications. This is due primarily to the density of traffic delivered to phones during times of peak demand. These physical limitations include free-space path loss, weak upload performance from omnidirectional phone antennas, beam diameter and indoor coverage.
Figure 2: Crown Castle tower asset example
Pictured is one of Crown Castle’s assets with three tenants. Crown Castle owns and manages the passive infrastructure (tower, the land and building under the tower) whereas the customers manage the active equipment (antenna, radios, fibre backhaul, etc.)
Source: CCI Company Documents
Those who have followed the industry closely would have noticed Elon Musk alluding to the possibility of a direct-to-cell satellite service (not to be confused with Starlink’s larger broadband satellite constellation) on par with traditional terrestrial wireless. Since then, telecom executives and radio frequency engineers have come out dismissing the potential for low-earth-orbit satellites to provide high-bandwidth cell service in metro areas directly to a mobile phone. The latest in this saga came in early October, when SpaceX announced that they may build “an advanced terrestrial deployment” to become “a major mobile carrier in the US”. This non-committal announcement caused a +16% 1-day move in CCI’s stock price as the market is speculating that Starlink could become a new customer on CCI’s towers. While we remain sceptical about this, we believe that this helps chip away at the tower disruption narrative.
Rates up, CCI down. Ultimately prospective returns improve from here
On fundamentals, interest rates have a limited impact on the operating cash flows of CCI as their revenues are the telco’s stay-in-business payments for essential services. However, interest rates do have an impact on equity returns in the form of higher borrowing costs as debt is refinanced. CCI has mitigated this with currently 100% fixed-interest-rate debt.
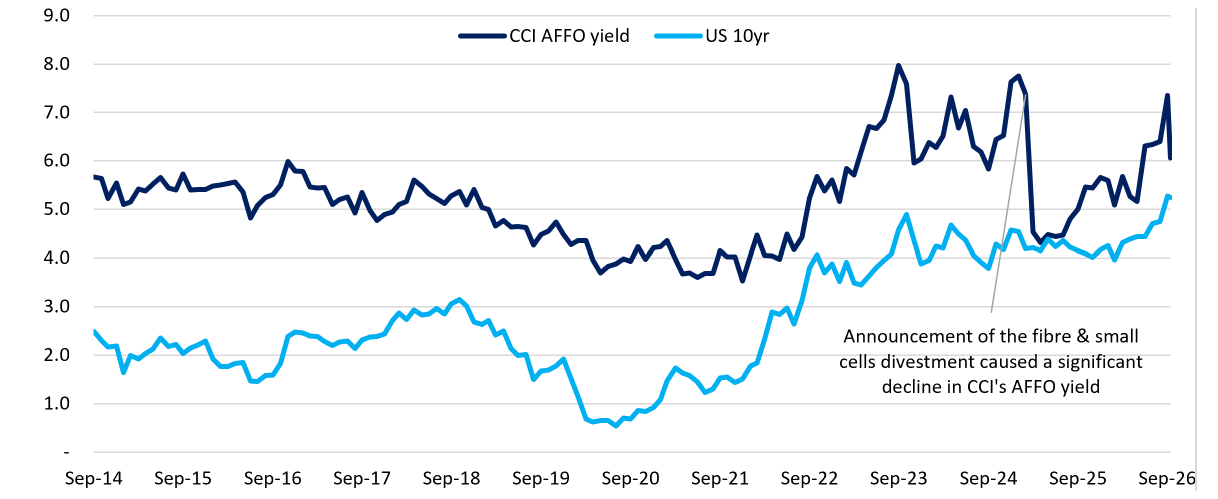
While fundamentals don’t change much, CCI’s stock price is inversely correlated to the US 10-year Treasury yield and it has undoubtedly been a loser as the 10-year bond yield increased from 1.51% at the end of 2021 to 5.24% today. Figure 3 shows how the Adjusted Funds From Operations (AFFO) yield of CCI has traded in lockstep with the 10-year yield because equity returns are viewed as low growth and “bond-like”.
Figure 3: Crown Castle (next 12 months) AFFO and the US 10-year Treasury yield
Higher interest rates are capitalised into CCI’s share price quickly. Shares fell by 15% during the 2Q & 3Q26 quarters primarily because the US 10-year yield increased by almost 1% (97bp), during a period in which CCI raised their FY2026 guidance.
Source: CCI Company Documents
Valuations of more exciting higher-growth companies can defy an increase in the cost of capital for longer periods of time. However, eventually a higher cost of capital environment slows investment and more cyclical business activity, whereas a higher cost of capital is capitalised into CCI’s share price almost instantly, therefore lifting prospective returns. While we cannot predict where interest rates go from here, should we see a downturn in economic activity, interest rates generally move lower and there is generally a defensive rotation in equity markets to companies with greater certainty of cash flows like CCI.
As we move past the headwinds of the past 5 years, the investment proposition is simple
The forecasted 2027 AFFO yield for CCI currently sits at 6.2%. Revenues are expected to grow at least 3% in a business with natural operating leverage. Therefore, our prudent case for shareholder returns (at current interest rate levels) is ~9% p.a. over our investment horizon. While CCI is often compared to high-yield credit as an investment proposition, we believe the differentiator in infrastructure equity is the duration of real growth that compounds over decades. Imagine a future with networks of autonomous vehicles, smart cities or abundant robotics without a high-speed and reliable terrestrial wireless network. Tower infrastructure is the foundation for this future.
Roy Harrison, Investment Analyst
Important Information:
This material is not intended to constitute advertising or advice of any kind and you should not construe the contents of this material as legal, tax, investment or other advice. In making an investment decision, you should read and consider any relevant offer documentation applicable to any investment product or service and must rely on your own examination of the same and consider obtaining professional investment advice tailored to your specific circumstances before making any investment decision.
The investment program of the strategy or strategies presented herein ('Strategy') is speculative and may involve a high degree of risk. The Strategy is not intended as a complete investment program and is suitable only for sophisticated investors who can bear the risk of loss. The Strategy may lack diversification, which can increase the risk of loss to investors. The Strategy's performance may be volatile. Past performance is not necessarily indicative of future results and no person guarantees the future performance of the Strategy, the amount or timing of any return from it, that asset allocations will be met, that it will be able to implement its investment strategy or that its investment objectives will be achieved. Statements contained in this material that are not historical facts are based on current expectations, estimates, projections, opinions and beliefs and such statements involve known and unknown risks, uncertainties and other factors, and undue reliance should not be placed thereon. This material may contain ‘forward-looking statements’. Actual events or results or the actual performance of the Strategy or any financial product or service may differ materially from those reflected or contemplated in such forward-looking statements. The Strategy will have limited liquidity, no secondary market for interests in the Strategy is expected to develop and there are restrictions on an investor's ability to withdraw and transfer interests in the Strategy. The management fees, incentive fees and allocation and other expenses of the Strategy will reduce trading profits, if any, or increase losses.
No representation or warranty is made with respect to the correctness, accuracy, reasonableness or completeness of any of the information contained in this material. This information is subject to change at any time and no person has any responsibility to update any of the information provided in this material. This material may include data, research and other information from third party sources. No guarantee is made that such information is accurate, complete or timely and no warranty is given regarding results obtained from its use. The issuer of this material and its related entities and affiliates will not be responsible or liable for any losses, whether direct, indirect or consequential, including loss of profits, damages, costs, claims or expenses, relating to or arising from your use or reliance upon any part of the information contained in this material including trading losses, loss of opportunity or incidental or punitive damages.
This material and the information contained within it may not be reproduced, or disclosed, in whole or in part in any circumstances. , Further information regarding any benchmark referred to herein can be found at www.magellaninvestmentpartners.com/funds/benchmark-information/. Any third-party trademarks contained herein are the property of their respective owners and are used for information purposes and only to identify the company names or brands of their respective owners. (060126-#i1)
United Kingdom: This material has been prepared by Magellan Asset Management Limited (ABN 31 120 593 946 AFSL 304 301) doing business as Magellan Investment Partners and is distributed in the United Kingdom by Magellan Investment Partners (UK) Limited (FRN: 1037936), an appointed representative of Sentinel Regulatory Services Ltd (FRN: 1007093) which is authorised and regulated by the Financial Conduct Authority. This material does not constitute an offer or inducement to engage in an investment activity under the provisions of the Financial Services and Markets Act 2000 (FSMA). This material does not form part of any offer or invitation to purchase, sell or subscribe for, or any solicitation of any such offer to purchase, sell or subscribe for, any shares, units or other type of investment product or service. This material or any part of it, or the fact of its distribution, is for background purposes only. This material has not been approved by a person authorised under the FSMA and its distribution in the United Kingdom and is only being made to persons in circumstances that will not constitute a financial promotion for the purposes of section 21 of the FSMA as a result of an exemption contained in the Financial Services and Markets Act 2000 (Financial Promotion) Order 2005 (FPO) as set out below. This material is exempt from the restrictions in the FSMA as it is to be strictly communicated only to 'investment professionals' as defined in Article 19(5) of the FPO.
United States: This material has been prepared by Magellan Asset Management Limited (ABN 31 120 593 946 AFSL 304 301) doing business as Magellan Investment Partners (‘Magellan’) which is a registered investment adviser. The investment strategies described herein are offered in the United States by Magellan Investment Partners North America, Inc., a U.S.-registered investment adviser. Magellan and Magellan Investment Partners North America, Inc. are affiliated entities for purposes of the Investment Advisers Act of 1940. Registration as an investment adviser does not imply any level of skill or training. This material is not intended as an offer or solicitation for the purchase or sale of any securities, financial instrument or product or to provide financial services. It is not the intention of Magellan to create legal relations on the basis of information provided herein. Past performance does not guarantee future results. Where performance figures are shown net of fees charged to clients, the performance has been reduced by the amount of the highest fee charged to any client employing that particular strategy during the period under consideration. Actual fees may vary depending on, among other things, the applicable fee schedule and portfolio size. Fees are available upon request and also may be found in Part 2 of Magellan’s Form ADV.
Canada: This material is provided to you by Magellan Asset Management Limited (ABN 31 120 593 946 AFSL 304 301) doing business as Magellan Investment Partners (‘Magellan’). Magellan is not registered in any province in Canada. The head office of Magellan is in Sydney, Australia and all or substantially all of its assets are situated outside of Canada. Due to the foregoing, there may be difficulty enforcing legal rights against Magellan.
South Africa: This material is provided to you by Magellan Asset Management Limited (ABN 31 120 593 946 AFSL 304 301) doing business as Magellan Investment Partners, who in accordance with FAIS Notice 55 of 2023 issued by the Financial Sector Conduct Authority, Magellan Investment Partners is exempted from section 7(1) of the Financial Advisory and Intermediary Services Act, 2002 (Act No. 37 of 2002). This material is not an offer in terms of Chapter 4 of the Companies Act, 2008.
UAE: This material has been produced by Magellan Asset Management Limited (ABN 31 120 593 946 AFSL 304 301) doing business as Magellan Investment Partners. This material is not for distribution to any other person. This material, and the information contained herein, does not constitute, and is not intended to constitute, a public offer of securities in the United Arab Emirates (‘UAE’) and accordingly should not be construed as such. Any offer of securities or financial services is made only to a limited number of exempt Professional Investors in the UAE who fall under one of the following categories: federal or local governments, government institutions and agencies, or companies wholly owned by any of them. No securities or services have been approved by or licensed or registered with the UAE Central Bank, the Securities and Commodities Authority, the Dubai Financial Services Authority, the Financial Services Regulatory Authority or any other relevant licensing authorities or governmental agencies in the UAE (the ‘Authorities’). The Authorities assume no liability for any investment that the named addressee makes as a Professional Investor. This material is for the use of the named addressee only and should not be given or shown to any other person (other than employees, agents or consultants in connection with the addressee’s consideration thereof).
Japan: This material is prepared by Magellan Asset Management Limited (ABN 31 120 593 946 AFSL 304 301) doing business as Magellan Investment Partners. The content is for informational purposes only and directed at Qualified Institutional Investors and other professional investors as defined in the Financial Instruments and Exchange Act. No distribution of this material will be made in any jurisdiction where such distribution is not authorised or is unlawful. This material does not constitute, and may not be used for the purpose of, an offer or solicitation in any jurisdiction or in any circumstances in which such an offer or solicitation is unlawful or not authorized or in which the person making such offer or solicitation is not qualified to do so.
Other jurisdictions: This material is provided to you by Magellan Asset Management Limited (ABN 31 120 593 946 AFSL 304 301) doing business as Magellan Investment Partners. No distribution of this material will be made in any jurisdiction where such distribution is not authorised or is unlawful. This material does not constitute, and may not be used for the purpose of, an offer or solicitation in any jurisdiction or in any circumstances in which such an offer or solicitation is unlawful or not authorized or in which the person making such offer or solicitation is not qualified to do so.